The public record of what the powerful say about the futureAll times UTCYour time ATHENA News Room is liveSealed daily · anchored in BitcoinΕλληνικά A Tekmerion product
THE ORACLE HUNTERS • EVERY PROPHECY ON THE RECORD •AAAWgmp1bWIAAAAeanVtZGMycGEAEQAQgAAAqgA4m3EDYzJwYQAAABZcanVtYgAAAEdqdW1kYzJtYQARABCAAACqADibcQN1cm46YzJwYTo4MTk5ZDlhYi0zYzIzLTQwZDYtYTc1NS04MTM5NWJhODhjMTYAAAADl2p1bWIAAAApanVtZGMyYXMAEQAQgAAAqgA4m3EDYzJwYS5hc3NlcnRpb25zAAAAALxqdW1iAAAARGp1bWRjYm9yABEAEIAAAKoAOJtxE2MycGEuaW5ncmVkaWVudC52MwAAAAAYYzJzaIxn7Lz8d2kiZVLVmLMqjH8AAABwY2JvcqNpZGM6Zm9ybWF0bWltYWdlL3N2Zyt4bWxqaW5zdGFuY2VJRHgseG1wOmlpZDpjNjQzY2M2MC03NmU5LTRkODUtODAzNi04Y2U2YmUwZDA0MzRscmVsYXRpb25zaGlwaHBhcmVudE9mAAAB4mp1bWIAAABBanVtZGNib3IAEQAQgAAAqgA4m3ETYzJwYS5hY3Rpb25zLnYyAAAAABhjMnNoYoNKEfN7QooyLxBggQwrRAAAAZljYm9yomdhY3Rpb25zgqJmYWN0aW9ua2MycGEub3BlbmVkanBhcmFtZXRlcnOha2luZ3JlZGllbnRzgaJjdXJseC1zZWxmI2p1bWJmPWMycGEuYXNzZXJ0aW9ucy9jMnBhLmluZ3JlZGllbnQudjNkaGFzaFggGR++KIZKhTpFlfMpaeP4xKARvK6IpGRCm/JKHJsg8z+kZmFjdGlvbngdY29tLmFudGhyb3BpYy5jbGF1ZGUucHJvdmlkZWRqcGFyYW1ldGVyc6F4H2NvbS5hbnRocm9waWMub3JpZ2luLWNvbmZpZGVuY2VndW5rbm93bmtkZXNjcmlwdGlvbnhmQ2xhdWRlIHByb3ZpZGVkIHRoaXMgZmlsZSBhdCB0aGUgcmVxdWVzdCBvZiBhIHVzZXIgYW5kIG1heSBoYXZlIGNyZWF0ZWQgb3IgbW9kaWZpZWQgdGhlIGZpbGUgY29udGVudHMubXNvZnR3YXJlQWdlbnShZG5hbWVmQ2xhdWRlcmFsbEFjdGlvbnNJbmNsdWRlZPUAAADIanVtYgAAAEBqdW1kY2JvcgARABCAAACqADibcRNjMnBhLmhhc2guZGF0YQAAAAAYYzJzaLTPAMahVK/46OuJ/Q+uuA8AAACAY2JvcqVjYWxnZnNoYTI1NmNwYWRMAAAAAAAAAAAAAAAAZGhhc2hYII7HF9R24wInyRZy4rI4Fw0mI4Rb/ZNxjfxeO7PO35j2ZG5hbWVuanVtYmYgbWFuaWZlc3RqZXhjbHVzaW9uc4GiZXN0YXJ0GQiaZmxlbmd0aBkeBAAAAj5qdW1iAAAAJ2p1bWRjMmNsABEAEIAAAKoAOJtxA2MycGEuY2xhaW0udjIAAAACD2Nib3KlY2FsZ2ZzaGEyNTZpc2lnbmF0dXJleE1zZWxmI2p1bWJmPS9jMnBhL3VybjpjMnBhOjgxOTlkOWFiLTNjMjMtNDBkNi1hNzU1LTgxMzk1YmE4OGMxNi9jMnBhLnNpZ25hdHVyZWppbnN0YW5jZUlEeCx4bXA6aWlkOjljYzUwMDc4LTgzMDctNDI0ZS04NjE4LTVmYTQzMmE1MWJmNHJjcmVhdGVkX2Fzc2VydGlvbnODomN1cmx4LXNlbGYjanVtYmY9YzJwYS5hc3NlcnRpb25zL2MycGEuaW5ncmVkaWVudC52M2RoYXNoWCAZH74ohkqFOkWV8ylp4/jEoBG8roikZEKb8kocmyDzP6JjdXJseCpzZWxmI2p1bWJmPWMycGEuYXNzZXJ0aW9ucy9jMnBhLmFjdGlvbnMudjJkaGFzaFggjvXIkXvJ7aXB5IwuH8TLLMTeq4OAYClzgZHySVCatNCiY3VybHgpc2VsZiNqdW1iZj1jMnBhLmFzc2VydGlvbnMvYzJwYS5oYXNoLmRhdGFkaGFzaFggIhTKhum+9R2LsXAUkQyOeb6aKanhapGjq6FRT3EaJ9V0Y2xhaW1fZ2VuZXJhdG9yX2luZm+jZG5hbWVvQW50aHJvcGljIEZpbGVzZ3ZlcnNpb25lMS4wLjBrc3BlY1ZlcnNpb25lMi40LjAAABA4anVtYgAAAChqdW1kYzJjcwARABCAAACqADibcQNjMnBhLnNpZ25hdHVyZQAAABAIY2JvctKEWQISogEmGCFZAgowggIGMIIBjaADAgECAhRA5aAK7sI50L64g/oGQgU9Z1UTADAKBggqhkjOPQQDAzBJMRcwFQYDVQQKEw5BbnRocm9waWMsIFBCQzEuMCwGA1UEAxMlQW50aHJvcGljIENvbnRlbnQgQ3JlZGVudGlhbHMgUm9vdCBDQTAeFw0yNjA4MDcxODQzNTZaFw0yODA4MDYxOTQzNTZaMEQxFzAVBgNVBAoTDkFudGhyb3BpYywgUEJDMSkwJwYDVQQDEyBBbnRocm9waWMgQ2xhdWRlIENvbnRlbnQgU2lnbmluZzBZMBMGByqGSM49AgEGCCqGSM49AwEHA0IABJh6CmvLUBgFFNU0vUKlOVtE6djd17L5SuwX0LemFisBM3dkd/3cyjxFA3Qo5S46fX0/ihY0VZ7mfb9KF703t5OjWDBWMA4GA1UdDwEB/wQEAwIHgDAVBgNVHSUEDjAMBgorBgEEAYPoXgIBMAwGA1UdEwEB/wQCMAAwHwYDVR0jBBgwFoAUzlHiBIFOZFsj+OPEz5o+nMHXXMIwCgYIKoZIzj0EAwMDZwAwZAIwMXMdFJ4BetLLVY7ORuE9noqbbAZOZn/aArXyTwFAZfKrPzxF2vPoJNf1+UCdg1XGAjBwX1zd9WGqYkqmL5SFqw1QySjr1zJfpJM9+1rdDwSPLMOPOjKuiXjoU/pUUeG9RwmhY3BhZFkNngAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAPZYQLfUpeT/MPsu1gA3RgZ8fvvIDmyZYJDWmz6ftVFNojm4kOQbEdCSTa0XP3aqZnboyhQ+RU/hD3bq8nBGJ+yvrXI=The Oracle HuntersEvery prophecy, on the record. · Οἱ Κυνηγοὶ τῶν ΧρησμῶνUnder development

← Tracking the Prophets

Vítor Constâncio

Bank of Portugal

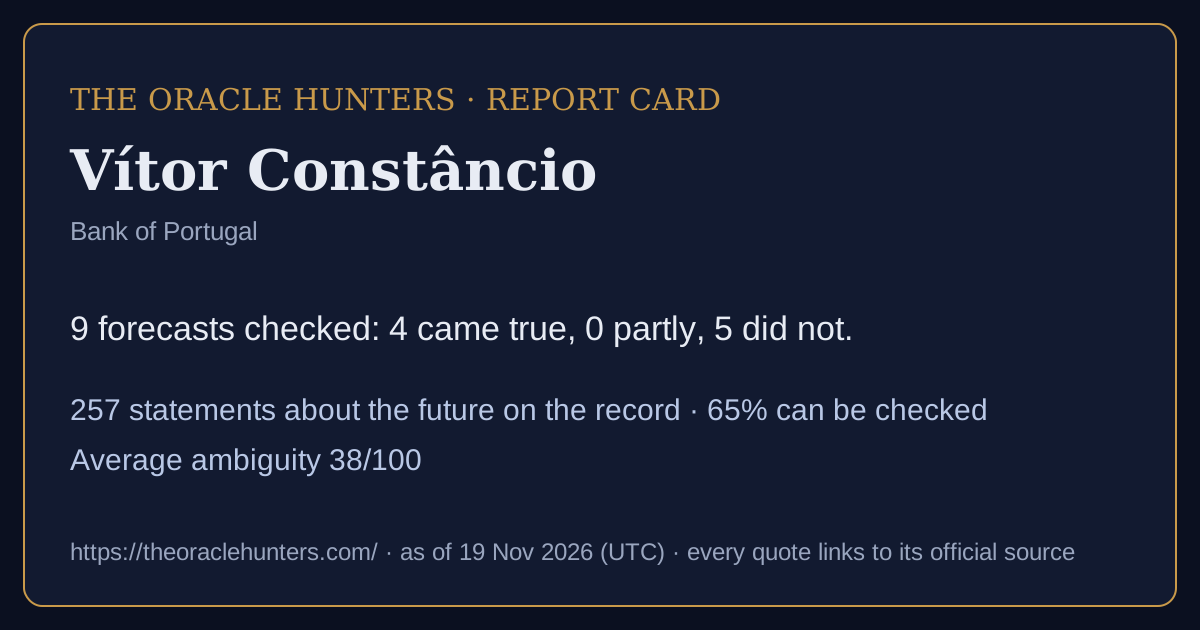
Track record: 9 forecasts checked: 4 came true, 0 partly, 5 did not.
257forecasts & commitments on the record
65%can be checked as stated
38average ambiguity (0-100)
0goalpost moves recorded
0confirmed U-turns

Timeline

20042004: Not due yet2004: Not due yet2005200620072008200920102010: Due - being checked2010: Due - being checked2010: Due - being checked2010: Due - being checked2010: Due - being checked2010: Not due yet2010: Not due yet2010: Due - being checked (+10 more)20112011: Did not come true2011: Due - being checked2011: Due - being checked2011: Not due yet2011: Due - being checked2011: Due - being checked2011: Not due yet2011: Not due yet (+10 more)20122012: Due - being checked2012: Due - being checked2012: Due - being checked2012: Due - being checked2012: Due - being checked2012: Due - being checked2012: Due - being checked2012: Due - being checked (+2 more)20132013: Did not come true2013: Not due yet2013: Due - being checked2013: Due - being checked2013: Due - being checked2013: Not due yet2013: Not due yet2013: Due - being checked (+15 more)20142014: Came true2014: Did not come true2014: Due - being checked2014: Due - being checked2014: Due - being checked2014: Due - being checked2014: Due - being checked2014: Not due yet (+42 more)20152015: Came true2015: Not due yet2015: Not due yet2015: Not due yet2015: Due - being checked2015: Not due yet2015: Due - being checked2015: Not due yet (+35 more)20162016: Came true2016: Did not come true2016: Did not come true2016: Due - being checked2016: Due - being checked2016: Not due yet2016: Due - being checked2016: Due - being checked (+27 more)20172017: Came true2017: Not due yet2017: Not due yet2017: Due - being checked2017: Not due yet2017: Not due yet2017: Due - being checked2017: Due - being checked (+30 more)20182018: Not due yet2018: Due - being checked2018: Due - being checked2018: Not due yet2018: Not due yet2018: Not due yet2018: Due - being checked2018: Not due yet (+12 more)
came true partly did not not due / being checked / too vague

Calibration score: shown after 10 checked forecasts with a stated likelihood (now 6).
How they speak about the future: based on data 195, stated on authority 40, educated guess 22.
Kinds of claim: forecast 199, mixed claim 32, scenario (if… then) 19, commitment 7. · Download this report card as a picture
In the nine words

πρόγνωσιςInference from evidence185 · 72%μαντείαInspired knowledge35 · 14%πρόνοιαPreparing for the future19 · 7%προαναγγελίαPublic pre-announcement7 · 3%εἰκασίαConjecture5 · 2%φρόνησιςPractical wisdom4 · 2%πρόβλεψιςSeeing the signs2 · 1%
How to read this Each box is one sentence a public figure or institution said about the future, word for word, with a link to the official text. Can be checked means it names what will happen, by when, and how likely - so it can be compared with official figures later. Too vague to check means it does not. Ambiguity (0-100) is how many different ways the sentence can be read. When the date passes, the forecast is compared with official data and marked came true, partly or did not come true. Labels judge the sentence, never the person. Full guide and glossary.

Checked

Annual real GDP is projected to increase by 2.2% in 2017, 1.8% in 2018 and 1.7% in 2019.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2018Came truegrowth
Came true. Said: economic growth around 1.8% in 2018. Official figure for Euro area: 1.8% (World Bank open data). On target. Off by 0.0 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
Regarding inflation, the latest ECB staff projections foresee a rise to 1.2% in 2017 and 1.6% in 2018.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 36/100below the RIM-1 standarddue 31 Dec 2017Came trueinflation
Came true. Said: inflation around 1.2% in 2017. Official figure for Euro area: 1.4% (World Bank open data). On target. Off by 0.2 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
Against this background, in the most recent ECB staff projections, real GDP is forecasted to grow at an annual rate of 1.7% in 2016 and 1.6% in 2017.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 36/100below the RIM-1 standarddue 31 Dec 2017Did not come truegrowth
Did not come true. Said: economic growth around 1.6% in 2017. Official figure for Euro area: 2.6% (World Bank open data). Missed. Off by 1.0 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
Real GDP is projected to grow at an annual rate of 1.7% in 2016, 1.6% in 2017 and 1.6% in 2018.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2017Did not come truegrowth
Did not come true. Said: economic growth around 1.6% in 2017. Official figure for Euro area: 2.6% (World Bank open data). Missed. Off by 1.0 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
Inflation ran at 0.8 percent last year in Germany, and is forecast to be only 0.2 percent this year.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2015Came trueinflation
Came true. Said: inflation around 0.2% in 2015. Official figure for Germany: 0.5% (World Bank open data). On target. Off by 0.3 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
Thereafter, the inflation rate is expected to increase gradually up to 1.4% in 2016, a level which is still below our price stability mandate defined as a rate of growth in the euro area HICP of below, but close to, 2%.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 36/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standarddue 31 Dec 2016Came trueinflationgrowth
Came true. Said: inflation below 1.4% in 2016. Official figure for Euro area: 0.1% (World Bank open data). On target. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
From 0.7% in 2014, inflation is expected to reach 1.1% in 2015 and, more uncertainly, 1.4% in 2016.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 36/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standarddue 31 Dec 2015Did not come trueinflation
Did not come true. Said: inflation around 1.1% in 2015. Official figure for Euro area: -0.1% (World Bank open data). Missed. Off by 1.2 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
The ECB’s staff projections estimate inflation for next year at 1.3%, which is below and not very close to 2%.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 36/100below the RIM-1 standarddue 31 Dec 2014Did not come trueinflation
Did not come true. Said: inflation around 1.3% in 2014. Official figure for Euro area: 0.2% (World Bank open data). Missed. Off by 1.1 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
At the same time, we expect inflation to return below 2% in the course of 2012.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2012Did not come trueinflation
Did not come true. Said: inflation below 2% in 2012. Official figure for Euro area: 2.6% (World Bank open data). Missed. Off by 0.6 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)

On the record (257)

They might have got 2.25% interest on their deposits before the euro was introduced, but inflation was also much higher back then, at 2.4%.
Central bank (via BIS) · said 29 May 2018 (date) · Interview with Spiegel Online · evidence & why
Market participants currently expect interest rates to change around the middle of next year.
Central bank (via BIS) · said 29 May 2018 (date) · Interview with Spiegel Online · evidence & why
μαντεία · Inspired knowledgePartly checkableForecaststated on authorityambiguity 56/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standarddue 31 Dec 2019Due - being checkedinterest rates
## All the same, can you give German savers reason to hope that interest rates will finally start to rise again in 2019?
Central bank (via BIS) · said 29 May 2018 (date) · Interview with Spiegel Online · evidence & why
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 85% · for the most partmeets the RIM-1 standarddue 31 Dec 2019Due - being checkedinterest rates
The double dip in growth experienced in 2012-2013 could have been significantly mitigated or avoided if such a European stabilisation function had been available.
πρόνοια · Preparing for the futurePartly checkableScenario (if… then)based on dataambiguity 56/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standardNot due yetgrowth
For instance, according to a recent working paper of the Peterson Institute, in order to have an expected five-year loss rate of 0.5% or lower, the European entity could securitise 50% of a country’s debt or 25% of its GDP. The benefits of having a European safe asset would be enormous to strengthen the overall resilience of the euro area.
This trend cannot continue indefinitely. […] Thus, the 3.71% increases in the wage settlements of government employees, which may turn out to be effective increases of 6% as in recent years, are a bad example, hardly reconcilable with the situation of public finances, and should not be followed by the remaining sectors of the economy.” All the illusions nurtured by …
What's not agreed at this sum m it next month might not be agreed for quite some time to come, depending on how Parliament changes.
Central bank (via BIS) · said 17 May 2018 (date) · Interview with Bloomberg TV · evidence & why
μαντεία · Inspired knowledgePartly checkableForecaststated on authorityambiguity 83/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standarddue 01 Jul 2018Due - being checked
So, what is happening is still within the bounds of the staff projections for the whole year, which nevertheless forecast growth above 2%.
Central bank (via BIS) · said 17 May 2018 (date) · Interview with Bloomberg TV · evidence & why
I have not read what he said, but let me remind you: the projections that have been published, they foresee a growth rate for next year around 2% and then 1.7% for 2020.
Central bank (via BIS) · said 17 May 2018 (date) · Interview with Bloomberg TV · evidence & why
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100below the RIM-1 standarddue 31 Dec 2020Due - being checkedgrowth
Particularly, of course in Greece, which recorded a deficit of 15% instead of an expected 5.6%, but also other countries.
Central bank (via BIS) · said 16 May 2018 (date) · Interview in the Financial Times · evidence & why
Then, third, there is the BRRD [Bank Recovery and Resolution Directive], which rules that if there will be any collapse of banks, then no bailouts by the public sector can be engineered - at least before there is a private bail-in of 8% of the total assets of the bank.
Central bank (via BIS) · said 16 May 2018 (date) · Interview in the Financial Times · evidence & why
I still believe that we will have the kind of growth that is forecast in our staff projections, so I am not worried too much about that as long as there is no extraordinary international event that derails world growth.
Central bank (via BIS) · said 16 May 2018 (date) · Interview in the Financial Times · evidence & why
Last year, Spain still had a primary deficit of 0.5%, but this year it is very likely that they will also make a surplus.
Central bank (via BIS) · said 16 May 2018 (date) · Interview in the Financial Times · evidence & why
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2018Due - being checkedfiscal
The reference value for M3 annual growth was calculated to be 4.5% and was used to produce a monetary overhang: the difference between actual M3 growth and the reference value, with higher numbers representing higher risks for medium term inflation.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100below the RIM-1 standardNot due yetinflationgrowth
For instance, according to a recent working paper of the Peterson Institute, in order to have an expected five-year loss rate of 0.5% or lower, the European entity could securitise 50% of a country’s debt or 25% of its GDP. Capital Markets Union, financial integration and economic growth A European safe asset is crucial for the CMU project which in …
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standardNot due yetgrowthfiscalfinancetrade
They argued that if expected inflation were to remain unaffected by an asset price bubble, which would be the case if the bubble was not too long lasting, then reacting only to expected inflation would not prevent bubble-induced macroeconomic volatility.
πρόνοια · Preparing for the futurePartly checkableScenario (if… then)educated guessambiguity 36/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standardNot due yetinflation
A fall in prices and an increase in yields, if sudden and disorderly, could be a threat.
Central bank (via BIS) · said 17 Jan 2018 (date) · Interview in La Repubblica · evidence & why
πρόνοια · Preparing for the futurePartly checkableScenario (if… then)educated guessambiguity 56/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standardNot due yetinflation
In the minutes of the December meeting it says that forward guidance 'could be revisited' early this year.
Central bank (via BIS) · said 17 Jan 2018 (date) · Interview in La Repubblica · evidence & why
μαντεία · Inspired knowledgePartly checkableForecaststated on authorityambiguity 56/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standarddue 31 Dec 2018Due - being checked
## Are there hidden risks in the current divergence between the Fed, which is expected to increase rates three times this year, and the ECB?
Central bank (via BIS) · said 17 Jan 2018 (date) · Interview in La Repubblica · evidence & why
μαντεία · Inspired knowledgePartly checkableForecaststated on authorityambiguity 36/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standarddue 31 Dec 2018Due - being checked
Does that mean that we should expect an increase in rates ahead of time, even this year?
Central bank (via BIS) · said 17 Jan 2018 (date) · Interview in La Repubblica · evidence & why
μαντεία · Inspired knowledgePartly checkableMixed claimstated on authorityambiguity 36/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standarddue 31 Dec 2018Due - being checked
This would increase the probability of crises and, in different scenarios, this could produce a GDP loss between 0.5 to 1.4%. Cline, W.
It is shown that a four percentage point increase in the capital ratio lowers this annual probability to less than 1%, while a one percentage point reduction in the annual probability of banking crises results in an expected drop in output of 0.6%.
Analysts’ earnings forecasts for 2017 and 2018 have been revised upwards since the U.S. elections, even if net interest income expectations have changed only marginally, despite improving economic conditions (volume effect) and (prospective) higher long-term interest rates (price effect).
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100below the RIM-1 standarddue 31 Dec 2018Due - being checkedinterest rateselections
The economic recovery, the expected steepening of the yield curve and even the progress being made in reducing the NPL level from the average peak of 8% in 2013 to the more recent average of 5.5%, have improved the market assessment of future banks’ profitability.
The estimates indicate that three years after the interest rate shock, the impact would represent a burden of 0.5% of household disposable income and about 2.5% of the gross revenues of non-financial firms, amounts that could be absorbed in the context of the ongoing recovery.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standardNot due yetinterest rates
The EONIA is expected to go above zero only in 2019 and reach 2% in ten years-time.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 36/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standarddue 31 Dec 2019Due - being checked
The European Commission expects deficits below 3% of GDP and positive primary surpluses in almost all euro area countries in 2018.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2018Due - being checkedgrowthfiscal
Euro area headline inflation stood at 1.5% in September 2017, according to Eurostat’s flash estimate and is expected to temporarily decline towards the turn of the year owing to energy-related base-effects.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 36/100implied call / likelihood: Yes · 70% · probablebelow the RIM-1 standardNot due yetinflationenergy
The inflation outlook from the recent IMF WEO depicts inflation at 1.5% in 2017 and 1.4% in 2018, which is broadly in line with ECB projections.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100below the RIM-1 standarddue 31 Dec 2018Due - being checkedinflation
Looking further ahead and according to the latest ECB staff projections, inflation is expected to rise to 1.5% in 2017, 1.2% in 2018 and 1.5% in 2019.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2018Due - being checkedinflation
According to the latest IMF WEO projections, euro area real GDP is expected to grow by 2.1% in 2017 before moderating to 1.9% in 2018 and 1.7% in 2019, which is in line with the ECB projections.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2018Due - being checkedgrowth
Annual real GDP is projected to increase by 2.2% in 2017, 1.8% in 2018 and 1.7% in 2019.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2018Came truegrowth
Came true. Said: economic growth around 1.8% in 2018. Official figure for Euro area: 1.8% (World Bank open data). On target. Off by 0.0 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
If banks cannot adjust the rates they pay their customers for their deposits as a reaction to falling loan rates, their profitability could decrease, leading to lower bank equity which in turn, could lead to lower lending, potentially hindering the pass-through of policy.
πρόνοια · Preparing for the futurePartly checkableScenario (if… then)educated guessambiguity 71/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standardNot due yetfinance
As you may recall, at the end of 2011 we decided to offer the euro area banking sector two additional LTROs with a maturity of 3 years and an interest rate as low as 1 percent, fixed over the maturity of the operation.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100implied call / likelihood: No · 40% · probablebelow the RIM-1 standardNot due yetinterest ratesfinance
Moreover, if innovation is endogenous hysteresis effects of a demand-led recession could lead to a protracted slowdown in productivity (e.g. Garga and Singh 2016).
πρόνοια · Preparing for the futurePartly checkableScenario (if… then)based on dataambiguity 56/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standardNot due yetgrowth
Indeed, another online survey showed that participants of the Sintra Forum were divided on this issue. 43% of voters indicated that technological innovation will have an insignificant impact on employment in the next 10 years. 28% felt that the net impact would be positive and an equal share that it would be negative.
Pancaro, “Bank profitability challenges in euro area banks: the role of cyclical and structural factors”, in ECB Financial Stability Review, May 2015. The total volume of transactions in the loan portfolio market – including also non-distressed portfolios – in Europe amounted to about €103 billion in 2016, which is less than 10% of the EU NPL stock.
Evidence from the market for bank deposits”, American Economic Review, Vol. 93, pp. 1152–1171. See ECB Financial Integration in Europe, May 2017. For instance, the share of the 5 largest credit institutions in total banking sector assets was just 43% in Italy compared to an average of 63% across the euro area countries (based on 2016 data).
In the case of the ECB, the inflation objective is to maintain in the medium-term a level below, but close to 2%.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100below the RIM-1 standardNot due yetinflation
The introduction of the risk adjustment creates, of course, the risk of inflation being above 2% during some protracted periods.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 71/100below the RIM-1 standardNot due yetinflation
The ECB aims to maintain price stability over the medium-term, with an announced objective of annual inflation below, but close to, 2%.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100below the RIM-1 standardNot due yetinflation
Applying a risk adjustment factor to the interest rate in the FRB/US model, the authors find that, with a 0.5 adjustment, and a real rate of 1%, an objective of 2% inflation could be attained with output closer to potential.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standardNot due yetinflationinterest ratesgrowth
The foreseen increase in wages in the baseline scenario is thus essential for the staff projections for growth and inflation to materialise in 2019.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 36/100below the RIM-1 standarddue 31 Dec 2019Due - being checkedinflationgrowthlabour
Likewise, lending volumes have increased considerably as growth in loans to firms recovered to 2.0% in February 2017, from ‑2.9% in May 2014, and for households to 2.3% from -0.1% over the same period.
Overall, since May 2014, i.e. immediately before our decision on a combination of measures to provide additional monetary policy accommodation and to support lending to the real economy, the decline in bank lending rates has amounted to almost 120 basis points for loans to firms, and around 110 basis points for housing loans.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 71/100implied call / likelihood: No · 40% · probablebelow the RIM-1 standardNot due yetinterest ratesfinancehousing
We had previously warned that headline inflation could decline after March-April as a result of the reduced statistical base effect of comparing this year’s price levels of oil and other commodities with their levels a year ago.
μαντεία · Inspired knowledgeCan be checkedForecaststated on authorityambiguity 36/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standarddue 31 Dec 2017Due - being checkedinflationenergy
Incoming data and sentiment indicators in the first quarter of this year suggest that the pace of growth may be gaining momentum.
πρόβλεψις · Seeing the signsCan be checkedForecastbased on dataambiguity 36/100implied call / likelihood: No · 40% · probablebelow the RIM-1 standarddue 31 Dec 2017Due - being checkedgrowth
According to our latest staff projections, inflation is expected to move towards 1.7% in 2019, but that assumes underlying inflation at 1.8% and wage growth at 2.4%.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 70% · probablemeets the RIM-1 standarddue 31 Dec 2019Due - being checkedinflationgrowthlabour
But it is too soon to declare complete success: we have yet to secure a sustained convergence in inflation towards our goal of close to but below 2% over the medium term.
πρόγνωσις · Inference from evidencePartly checkableForecastbased on dataambiguity 56/100below the RIM-1 standardNot due yetinflation
Without the foreseen increase in wages, the baseline scenario of our staff projections for growth and inflation will not materialise in 2019.
πρόγνωσις · Inference from evidenceCan be checkedForecastbased on dataambiguity 0/100implied call / likelihood: Yes · 85% · for the most partmeets the RIM-1 standarddue 31 Dec 2019Due - being checkedinflationgrowthlabour

Showing the newest 50 - the ledger has all 257.

Also said - not checkable as stated (12 newest)

Remarks about the future with no date, figure or likelihood that could be checked. They are kept on the record and shown here, but not scored.

The Governing Council of the ECB decided that the Eurosystem will continue to purchase assets at a rate of €30 billion each month until the end of September, and that interest rates should remain at their current levels beyond the end of the purchase programme.
Central bank (via BIS) · said 29 May 2018 (date) · Interview with Spiegel Online · evidence & why
Interview with Mr Vítor Constâncio, Vice-President of the European Central Bank, and Spiegel Online, conducted by Mr Stefan Kaiser and Mr Henning Jauernig on 22 May 2018 and published on 29 May 2018.
Central bank (via BIS) · said 29 May 2018 (date) · Interview with Spiegel Online · evidence & why
The reaction to the financial and sovereign debt crisis could have been quicker, and more flexible.
Central bank (via BIS) · said 29 May 2018 (date) · Interview with Spiegel Online · evidence & why
I am not really expecting that whatever happens in that sphere will have a very meaningful impact on what we will do.
Central bank (via BIS) · said 17 May 2018 (date) · Interview with Bloomberg TV · evidence & why
Interview with Mr Vítor Constâncio, Vice-President of the European Central Bank, and Bloomberg TV, conducted by Mr Paul Gordon on 17 May 2018.
Central bank (via BIS) · said 17 May 2018 (date) · Interview with Bloomberg TV · evidence & why
You may recall that the staff projections that were published, after the high growth of last year, already pointed to a certain deceleration.
Central bank (via BIS) · said 17 May 2018 (date) · Interview with Bloomberg TV · evidence & why
The authors recognise the sensitivity of the issue and write: ”When introducing such a policy, it is essential to ensure that it does not give rise to the expectation that some of the present debts of high-debt countries will inevitably be restructured, triggering financial instability in debt markets.” However, they acknowledge there is no simple solution to this transition problem.
EU Commission Vice-President Frans Timmermans wrote amid the refugee and migration pressures and the euro crisis of 2015: “It is the first time, in my conscious experience of European co-operation that I think the project could really fail”. Since then, the winds of populist nationalism have continued to advance.
Monetary union could almost be seen as a vast currency board devised to extend the benefit of price stability to the whole euro area.
εἰκασία · ConjectureToo vague to checkSpeculationeducated guessambiguity 71/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standardinflation
## What are you going to be watching in the coming months, from outside the ECB, in terms of trying to judge the health of the eurozone economy?
Central bank (via BIS) · said 16 May 2018 (date) · Interview in the Financial Times · evidence & why
μαντεία · Inspired knowledgeToo vague to checkForecaststated on authorityambiguity 56/100implied call / likelihood: Yes · 80% · for the most partbelow the RIM-1 standarddue 12 Nov 2018 (vague)health
We thought we could just target inflation, now you are saying the next generation has to consider all of these different preferences of agents, multiple equilibria, inequality...
Central bank (via BIS) · said 16 May 2018 (date) · Interview in the Financial Times · evidence & why
πρόνοια · Preparing for the futureToo vague to checkCall for actionstated on authorityambiguity 71/100implied call / likelihood: No · 35% · probablebelow the RIM-1 standardinflation
Monetary policy will certainly require the help of strong fiscal policy that will then need to be in place.
πρόνοια · Preparing for the futureToo vague to checkCall for actionstated on authorityambiguity 56/100implied call / likelihood: Yes · 85% · for the most partbelow the RIM-1 standardinterest ratesfiscal