Ryozo Himino
Bank of Japan
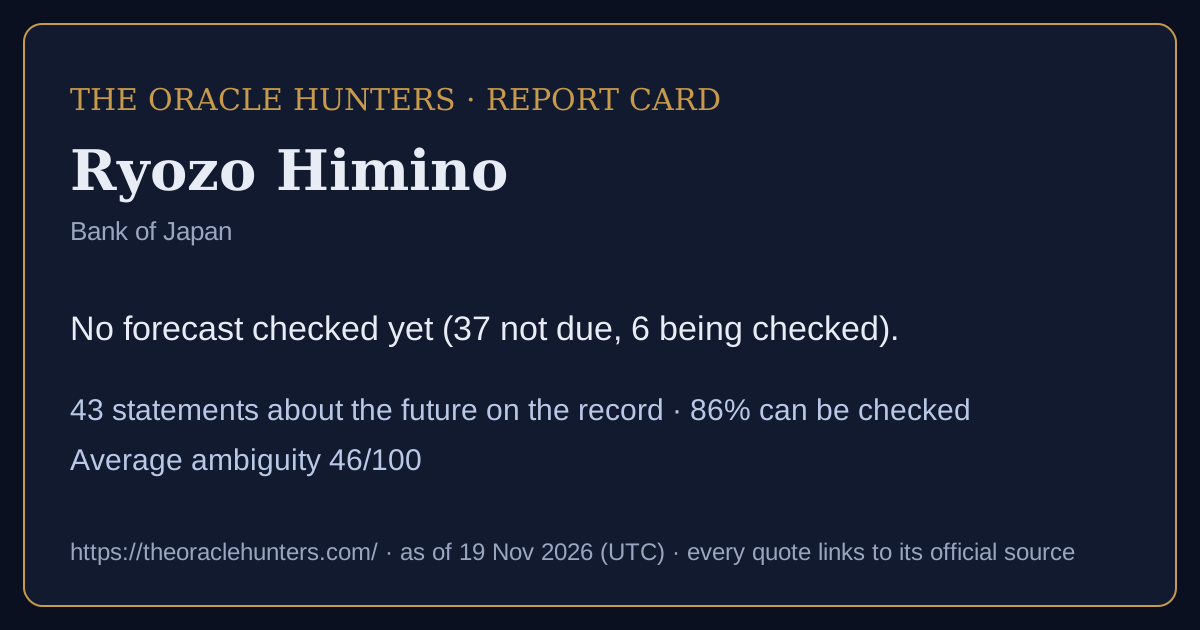
Track record: No forecast checked yet (37 not due, 6 being checked).
43forecasts & commitments on the record
86%can be checked as stated
46average ambiguity (0-100)
0goalpost moves recorded
0confirmed U-turns
Timeline
came true partly did not not due / being checked / too vague
Calibration score: shown after 10 checked forecasts with a stated likelihood (now 0).
How they speak about the future: based on data 40, educated guess 3.
Kinds of claim: forecast 34, mixed claim 8, scenario (if… then) 1. · Download this report card as a picture
In the nine words
πρόγνωσιςInference from evidence39 · 91%εἰκασίαConjecture2 · 5%πρόβλεψιςSeeing the signs1 · 2%πρόνοιαPreparing for the future1 · 2%
How to read this
Each box is one sentence a public figure or institution said about the future, word for word, with a link to the official text. Can be checked means it names what will happen, by when, and how likely - so it can be compared with official figures later. Too vague to check means it does not. Ambiguity (0-100) is how many different ways the sentence can be read. When the date passes, the forecast is compared with official data and marked came true, partly or did not come true. Labels judge the sentence, never the person. Full guide and glossary.On the record (43)
The five hyperscalers (Amazon, Microsoft, Alphabet, Meta, and Oracle) alone are expected to make capital investments amounting to 0.8 trillion dollars (around 130 trillion yen) in 2026, and much of this new investment is estimated to be AI related.
Baseline scenario | In line with expectations in futures markets, Dubai crude oil prices will decline from around 105 U.S. dollars per barrel to the range of around 70-80 dollars per barrel toward the end of the projection period (FY 2026 to 2028). |
From fiscal 2027 onward, Japan's economic growth rate is expected to rise moderately, since it is projected that the adverse effects of high crude oil prices will wane and that the virtuous cycle from income to spending will gradually intensify.
As for the conduct of monetary policy, given that underlying CPI inflation has been approaching 2 percent and financial conditions have been accommodative, the Bank will continue to raise the policy interest rate and adjust the degree of monetary accommodation, in response to developments in economic activity and prices as well as financial conditions.
However, given the movement of these indicators, I believe we are entering a phase where we will also need to bear in mind the possibility of underlying inflation exceeding 2 percent in addition to these considerations when making policy decisions.
Taking these factors into account, it is expected that CPI inflation will move up and stay above 2 percent in the second half of fiscal 2026.
With the price stability target of 2 percent, the Bank will conduct monetary policy as appropriate from the perspective of sustainable and stable achievement of the target.
On the price front, there appears to be a risk that price increases stemming from high crude oil prices will spread across a wide range of items, as well as a risk that underlying CPI inflation will deviate upward to a level above the price stability target of 2 percent.
However, the rate of increase is likely to accelerate to a level clearly above 2 percent, as the rise in crude oil prices is expected to push up prices, mainly of energy and goods.
Meanwhile, underlying CPI inflation is expected to increase gradually, coming to a level that is generally consistent with the price stability target between the second half of fiscal 2026 and fiscal 2027.
As for the future conduct of monetary policy, given that underlying CPI inflation has been approaching 2 percent and financial conditions have been accommodative, the Bank will continue to raise the policy interest rate and adjust the degree of monetary accommodation, in response to developments in economic activity and prices as well as financial conditions.
In line with the view in the Bank's Outlook Report, let's assume that inflation expectations will move toward 2 percent.
Over time, they are both expected to converge on a plateau marked with the 2 percent price stability target, and continue to proceed generally consistent with that level.
Following the earlier section projecting that the actual inflation rate will temporarily fall below 2 percent, the Outlook Report states (Chart 8 [left-hand panel]):
As to whether underlying inflation has reached the price stability target of 2 percent, however, while one might broadly assess that it is already close to 2 percent, I feel that asserting that the rate has reached 2 percent for certain may still be premature.
The year-on-year rate of increase in the consumer price index (CPI, all i less fresh food) is likely to decel level below 2 items less fresh food) is likely to decelerate to a level below 2 percent in the first half of this year, with the waning of the effects of the rise in food prices, such as rice prices, …
The year-on-year rate of increase in the consumer price index (CPI, all items less fresh food) is likely to decelerate to a level below 2 percent in the first half of this year, with the waning of the effects of the rise in food prices, such as rice prices, and partly due to the effects of government measures to address …
The rise may experience some temporary halts, but the mechanism in which wages and prices rise in interaction with each other will be maintained and eventually push up the underlying inflation rate to 2 percent.
Our baseline scenario at this point is as follows: The actual inflation rate, driven notably by a rise in rice prices and its transmission to other items, currently exceeds the 2 percent price stability target by a considerable margin, but will decline in due course.
Indeed, the International Monetary Fund (IMF) projected in July a growth rate of the global economy for 2025 that was lower by 0.3 percentage points than the projection it released in January, and stated that risks to the outlook are tilted to the downside.
The Bank will conduct an interim assessment of the plan at the June 2026 MPM.
- Until January-March 2026 : about 400 billion yen (the reduction plan decided in July 2024 will be maintained)
However, if hasty reductions in purchases result in a rapid rise in long-term interest rates and in the need to conduct an ad-hoc increase in the purchase amount, fixed-rate purchase operations, or the Funds-Supplying Operations against Pooled Collateral, this could harm market functioning even more.
By end -2021, 95 percent of mortgages carried low, fixed rates.
- CPI inflation is likely to be at around 2.5 percent for fiscal 2025, due to the higher import prices stemming from the yen's depreciation etc.
In the United States, inflation expectations had been anchored at 2 percent, but soaring commodity prices as well as narrower slack resulting from the economy's recovery from the pandemic and fiscal stimulus caused a sharp rise in inflation, which posed the risk that inflation expectations could be de -anchored to the upside.
Where inflation expectations are not anchored at 2 percent, the central bank will consider how they could be anchored.
If this outlook will continue to be realized, the Bank will raise the policy interest rate accordingly and adjust the degree of monetary easing, as it did in March and July last year.
The path we have drawn is a difficult one, in which the actual inflation rate will decline and inflation expectations will rise, and both will land at around 2 percent.
At the same time, if inflation expectation does not rise toward 2 percent, the actual inflation rate will eventually fall below 2 percent, and it thus would not be possible to achieve the target in a sustainable and stable manner.
The main scenario the Bank of Japan envisages is that the inflation rate for the next two fiscal years (April to March) will be around 2 percent (Chart 9).
The first question is whether the inflation rate will really moderate and reach the 2 percent target.
The Bank of Japan expects the real GDP to grow at a moderate rate of 0.6 percent this fiscal year, as the recovery process from the pandemic draws near to completion.
The Bank will conduct an interim assessment of the plan at the June 2025 MPM.
The question is whether wage hikes will continue in fiscal 2025 and after.
According to our forecast, these developments will gain traction from the middle of the fiscal year, and the real GDP will grow at around | percent in fiscal 2025 and 2026, a level that is slightly above the potential growth rate (Chart 1).
We, however, expect that inflation will gradually decelerate and that the CPI inflation rate for fiscal 2025 and 2026 will be at around 2 percent, in line with the target.
In recent months, the import price index has declined more than 10 percent compared to a year ago, and thus if the firms just stop at stage 1 -- a pass-through of higher import prices -- the Japanese economy may revert to the former deflationary state.
The prices of food and other frequently purchased daily necessities are rising at even higher rates, making many households feel burdened by even more than the 3 percent rate may imply.
Realizing such economic conditions has been a long-standing goal of the country and should be considered as a positive development in itself, but, if this happens, the Bank will likely gradually revise the large-scale monetary easing it has implemented to date.
Toward the end of the projection period, the Bank expects that underlying CPI inflation will increase gradually toward achieving the price stability target of 2 percent, while this increase needs to be accompanied by an intensified virtuous cycle between wages and prices.
The former, which is closer to the actual makeup of household budgets, was at around 3 percent in fiscal year 2022 and is projected to stay around the level for fiscal years 2023 and 2024, exceeding the price stability target of 2 percent.
The Bank plans to issue a new series of banknotes around the first half of July 2024, but the current series will remain valid, and we will continue to see Fukuzawa notes in circulation.
Also said - not checkable as stated (12 newest)
Remarks about the future with no date, figure or likelihood that could be checked. They are kept on the record and shown here, but not scored.
With regard to the outlook, while higher crude oil prices are likely to exert downward pressure on economic activity, Japan's economy is expected to be supported by factors such as high levels of corporate profits.
integrated into the payment system, and fund transfers between stablecoins and bank deposits may become systemic, enhancing the need to ensure singleness between the two types of money, under both normal and stressed conditions.
But perhaps I should take pride in my old-fashioned fat wallet, which may symbolize the emerging lifestyle of the era of geopolitical tensions.
10 In practice, to successfully complete a transaction, other issues may also need to be addressed.
For example, stablecoin business models might not be sustainable under zero or negative interest rates. 4 CBDCs may find it difficult to attract general users under unstressed conditions. 5
In March, Sweden's Riksbank, the world's oldest central bank and a pioneer in CBDC, published new recommendations for public payment preparedness (Chart 3, left). 6 The recommendations state, "The current international situation and Sweden's high degree of digitalization may lead to vulnerabilities in the payments system.
This is a topic under discussion both within the Bank and in international forums, and so some of the points I make will inevitably reflect my personal views rather than the views of the Bank or the consensus among central banks.
The results of the assessments are particularly consequential for countries that may have to rely on the IMF or the World Bank for support.
Today, there may be more need to tailor our approach to the demands of the task and the circumstances, and to be agile in seizing the opportunities that arise.
But if that were all it took, then a group of brilliant academics could simply draft good rules and the job would be done.
The implicit message was that those banks failing to meet the standards to be set by the two might no longer be able to operate in New York and London.
The next year, the Basel Committee reached an agreement.