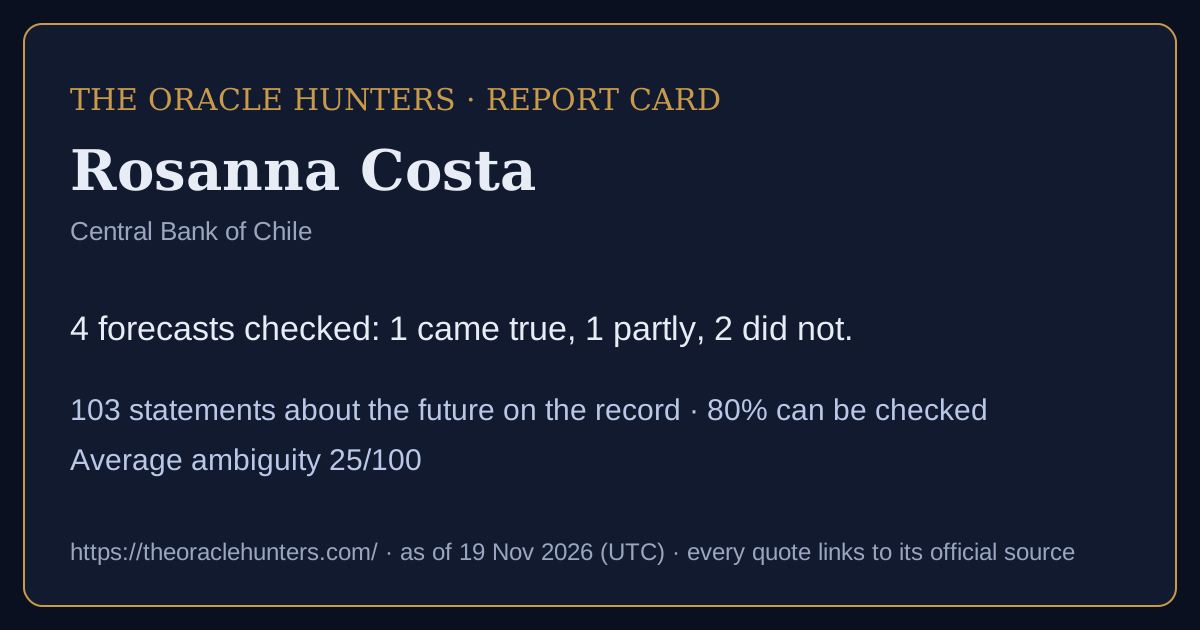
Rosanna Costa
Central Bank of Chile
Track record: 4 forecasts checked: 1 came true, 1 partly, 2 did not.
103forecasts & commitments on the record
80%can be checked as stated
25average ambiguity (0-100)
0goalpost moves recorded
0confirmed U-turns
Timeline
came true partly did not not due / being checked / too vague
Calibration score: shown after 10 checked forecasts with a stated likelihood (now 4).
How they speak about the future: based on data 93, stated on authority 8, educated guess 2.
Kinds of claim: forecast 94, mixed claim 7, scenario (if… then) 2. · Download this report card as a picture
In the nine words
πρόγνωσιςInference from evidence91 · 88%μαντείαInspired knowledge7 · 7%πρόβλεψιςSeeing the signs3 · 3%πρόνοιαPreparing for the future2 · 2%
How to read this
Each box is one sentence a public figure or institution said about the future, word for word, with a link to the official text. Can be checked means it names what will happen, by when, and how likely - so it can be compared with official figures later. Too vague to check means it does not. Ambiguity (0-100) is how many different ways the sentence can be read. When the date passes, the forecast is compared with official data and marked came true, partly or did not come true. Labels judge the sentence, never the person. Full guide and glossary.Checked
This year, GDP is expected to grow between 2.25% and 3.0%.
Came true. Said: economic growth between 2.25% and 3% in 2024. Official figure for Chile: 2.8% (World Bank open data). On target. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
On the growth side, for this year, we project that GDP will grow between -0.5% and +0.25%.
Partly came true. Said: economic growth between -0.5% and 0.25% in 2023. Official figure for Chile: 0.7% (World Bank open data). Close: outside the margin, but within one more half point. Off by 0.4 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
In the central scenario, GDP will grow 2.4% in 2022, then fall between -1.75% and -0.75% in 2023 and recover between 2% and 3% in 2024.
Did not come true. Said: economic growth between -1.75% and -0.75% in 2023. Official figure for Chile: 0.7% (World Bank open data). Missed. Off by 1.4 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
Furthermore, in our forecasts, which that I will detail in a few minutes, we anticipate that the annual variation of the CPI will approach levels in the order of 10% by the middle of this year.
Did not come true. Said: inflation around 10% in 2022. Official figure for Chile: 11.6% (World Bank open data). Missed. Off by 1.6 points. official data · checked 14 Nov 2026 · automatic check against official data (rules v3)
On the record (103)
As a result, in this IPoM, we once again revises down our growth outlook for this year.
Looking back at late 2025, we expected inflation to remain around 3% for much of this year and economic activity to grow between 2% and 3%.
Meanwhile, local mutual funds have increased their holdings of bank bonds, which could affect the value of these instruments in the event of significant redemptions.
In May 2023, the CCyB was activated for the first time , setting it at 0.5% of the banks' risk-weighted assets ( RWA s).
For its part, the regulation recently issued by the Superintendency of Pensions, which will take effect in 2027, is aimed at limiting pension funds' exposure to derivatives, and the amendment to the mutual fund liquidity regulations for General Fund Administrators announced in t he CMF's work plan.
In August, its annual variation stood at 3.9%, higher than a few months before and the projections made in our June monetary policy report.
Before moving on to the next part of my presentation, I would like to reiterate that the Central Bank of Chile will conduct monetary policy to ensure that inflation converges to the 3% target, which is a fundamental aspect of macroeconomic stability and the people's well-being.
Moving on to inflation, the annual variation in headline CPI has continued to decline as expected, reaching 4% annually in August.
Considering all these factors, we forecast only slightly larger headline inflation for the next year.
All in all, we expect headline CPI to converge to the 3% target in the third quarter of 2026, roughly a quarter later than our June forecast.
About commodity prices, our copper price projection remains unchanged at around US$4.3 per pound between 2025 and 2027.
Thus, in May, the annual variation of total and core CPI reached 4.4% and 3.6%, respectively (4.7% and 3.9% in February).
The greater dynamism anticipated for investment will be centered mainly on large mining and energy projects, whose planned amounts are revised with special emphasis for the second half of this year.
In this scenario, core inflation will stand around 3% towards the end of 2025 (Figure 14).
The inflation trajectory is mostly unchanged from our March forecast, so it is still expected to touch the 3% mark in the first half of 2026.
GDP is still expected to evolve around the trend in the coming quarters, with inflation converging to 3% in the first half of 2026.
In this rapidly evolving world-one that may reach unimaginable heights-our 2023-2027 Strategic Plan includes a key objective, that is, to continue deepening the use and analysis of data across all areas of the institution.
The next benchmark revision, for the year 2023, will be published in March 2027.
As part of Basel III, in May 2023, the Central Bank activated the Countercyclical Capital Buffer at 0.5% of risk weighted assets.
Official projections indicate that, in the short term, the latter will be slightly below the cap of 45% of GDP defined as prudent by the authorities.
This regulation, to be issued by the Central Bank, will be put out for public consultation during the first half of this year.
About our banks, the implementation of Basel III will be completed by the end of the year, thereby increasing the soundness and resilience of the banking system.
In addition, as we communicated in November last year, the first Financial Policy Meeting in 2026 the start of the convergence towards the neutral level of 1% of RWAs will be evaluate.
Thus, the activity gap has closed, the current account deficit has been significantly reduced and, although inflation remains high, the outlook for convergence to the 3% target by early 2026 is reaffirmed (Figure 5).
As I have just shown you, this means that, in the central scenario, inflation will fluctuate around 5% during the first half of 2025.
The latter also affects the estimate of 2.3% growth for this year, at the lower end of the range forecast in September (2,25-2,75%) (Table 1).
The GDP growth ranges forecast for 2025 and 2026 remain at 1.5%-2.5%.
In the central scenario, annual inflation will rise in the coming months, oscillating around 5% during the first half of 2025.
As I said, core inflation leads the revisions, with average inflation in 2025 to be 0.5 percentage points higher than forecast in September.
The annual variation of the CPI reached 4.2% in November and in the projections of this Report we foresee that it will close the year at 4.8%, to then fluctuate around 5% during the first half of 2025.
This could occur if protectionist trade policies are implemented that increase trade restrictions or disruptions in the supply chain and the commodities market.
convergence to Basel III, which will take place at the end of 2025.
Regarding the transition from its current level (0.5% of RWAs) to its neutral level (1.0% of RWAs), this process will occur gradually once the convergence to Basel III standards is completed in December 2025.
About the government, official projections indicate that during the period 2025-2029 the public debt will remain below the level that the authority has defined as prudent.
At our first financial policy meeting in 2026 we will assess the start of convergence towards the NCCyB, a definition that will be adopted to the extent that macro-financial conditions allow and considering a period of at least one year for its gradual construction.
The GFCF growth projection for the 2024 -2026 period is somewhat lower than the one considered in June, as a result of the weakness of investment in the non -mining sectors.
We estimate that its convergence to the 3% target will occur in the first months of 2026, to remain there until the end of the policy horizon (Figure 8).
By 2025 and 2026, private consumption is expected to grow at a pace in the order of 2% per year.
For 2025 and 2026, growth projections remain in a range between 1.5% and 2.5% (Table 1).
Trend GDP growth will slow over the course of the next decade, averaging 1.8% over the 2025 -2034 period.
By the end of this year, headline inflation is expected to close at 4.5% (4.2% forecast in June).
Our GFCF growth forecast for the period 2024-2026 is lowered some from June, due to weak non-mining investment.
This navigation chart considers one of the most historically relevant milestones for our institution: on 22 August next year the Central Bank of Chile will commemorate its centenary, 100 years since it was created during the administration of President Arturo Alessandri Palma.
Here I would like to pause on one point: although inflation will rise towards the end of the year and into 2025, this will be transitory and, if the projected scenario occurs, it will converge to the 3% target at the beginning of 2026.
At the end of this year, headline inflation is expected to close at 4.5% (4.2% in June).
Towards 2025 and 2026, private consumption is expected to grow around 2% per year, in line with trend growth.
On this occasion, we estimate that non-mining trend GDP growth will average 1.8% in the 2025-2034 period.
In the medium term, financial conditions are expected to improve and the information from the latest survey of the Capital Goods Corporation, which includes a10% increase in investments in the period 2024-2027 (Figure 10).
After analyzing the background information available following the publication of the Law on Electric Price Stabilization, it is expected that this increase will add 1.45 percentage points to cumulative inflation as of June 2025.
The main developments since March are: the improved starting point of domestic demand, which will be supported by the higher copper price, and the adjustment of electricity prices, which will significantly impact inflation, especially in 2025.
Showing the newest 50 - the ledger has all 103.
Also said - not checkable as stated (12 newest)
Remarks about the future with no date, figure or likelihood that could be checked. They are kept on the record and shown here, but not scored.
While the global economy proved more resilient than expected, supported by investment associated with the development and adoption of artificial intelligence, the Chilean economy lost momentum.
Going forward, we estimate that the economy will return to higher expansion rates, supported by a rebound in investment that would be underpinned, among other factors, by the recently approved Reconstruction Law and high copper prices.
However, it should be noted that the higher concentration of debt maturities in the coming years exposes local bond issuers to the risk of refinancing liabilities under unfavorable terms.
Rosanna Costa Governor Central Bank of Chile 19 May 2026
We conduct an analysis related to the fulfillment of the second mandate in our semiannual Financial Stability Report, which is published in May and November.
Furthermore, we communicated that we will evaluate the next movements of the MPR considering the evolution of the macroeconomic scenario and its implications for inflationary convergence.
Over the next two days, we will explore successful experiences in the use of data and artificial intelligence for more informed and timely decisionmaking.
Likewise, data collection sources will multiply, and historical series could be continuously updated, eliminating the need to wait years for final versions.
We will see how data is being used to gain deeper insights into economic and social phenomena, anticipate trends, identify opportunities, and mitigate risks.
The IMF was tasked with promoting international monetary cooperation, supporting trade expansion and economic growth, and discouraging policies that could harm global macroeconomic stability and nations' welfare.
Among the upcoming challenges, it will have to continue managing the increase in the portfolio's credit risk and its preparation for full
I am confident that the fruitful discussions we will have during this conference will deepen our understanding of these determinants and clarify where natural rates and other relevant interest rates may stand in the years ahead.