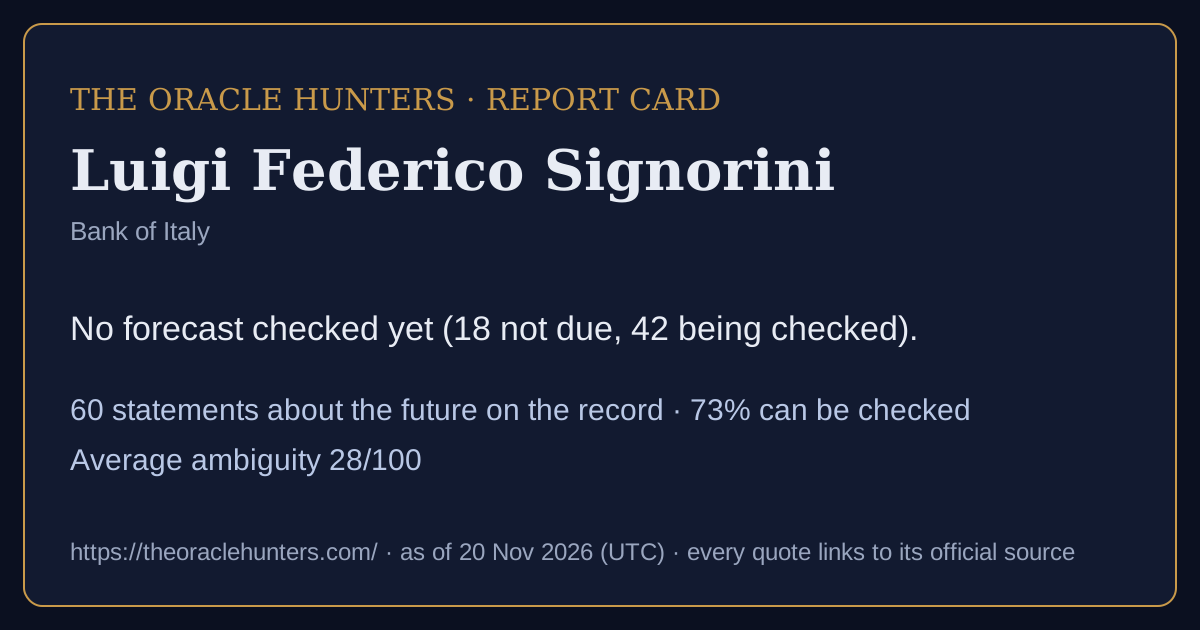
Luigi Federico Signorini
Bank of Italy
Track record: No forecast checked yet (18 not due, 42 being checked).
60forecasts & commitments on the record
73%can be checked as stated
28average ambiguity (0-100)
0goalpost moves recorded
0confirmed U-turns
Timeline
came true partly did not not due / being checked / too vague
Calibration score: shown after 10 checked forecasts with a stated likelihood (now 0).
How they speak about the future: based on data 53, stated on authority 4, educated guess 3.
Kinds of claim: forecast 49, mixed claim 7, scenario (if… then) 3, commitment 1. · Download this report card as a picture
In the nine words
πρόγνωσιςInference from evidence52 · 87%μαντείαInspired knowledge4 · 7%πρόνοιαPreparing for the future3 · 5%προαναγγελίαPublic pre-announcement1 · 2%
How to read this
Each box is one sentence a public figure or institution said about the future, word for word, with a link to the official text. Can be checked means it names what will happen, by when, and how likely - so it can be compared with official figures later. Too vague to check means it does not. Ambiguity (0-100) is how many different ways the sentence can be read. When the date passes, the forecast is compared with official data and marked came true, partly or did not come true. Labels judge the sentence, never the person. Full guide and glossary.On the record (60)
By 2050, one person in four will be African. 1 By 2030, half of all new entrants to the world's labour force will come from Sub-Saharan Africa. 2 This demographic transformation is both an immense opportunity and a major responsibility.
The U.K. and U.S. are also advancing with their national implementation, with rules expected to apply later in 2025.
After more than two years of negotiations, the process is nearing completion in the European Union, with the new rules expected to take effect at the start of next year.
increased if provision was made for automatic adjustment in tax rates with changes in income but this could hardly be called built-in flexibility in the usual sense of the term".
Given that wage growth (among other things) reacts to inflation with a certain degree of inertia, due to the lagged and staggered nature of wage bargaining, the high inflation rates of recent years could in principle give rise to delayed second-round effects; this would be of particular concern if further supply shocks were to materialise.
Our economists estimate that they could double in 2023-2024 compared with this year.
Some 20 per cent of total bank bonds outstanding will mature in the coming year.
Global economic activity is, in fact, slowing down and growth estimates for next year have been progressively revised downwards by leading international institutions.
According to the preliminary estimate released by Istat on 31 October, GDP increased slightly (0.5 per cent) in the third quarter too, once again surprising analysts, who had, at most, expected stagnation.
Nevertheless, despite the challenging situation, based on the projections in the latest issue of the Bank of Italy's Economic Bulletin - which will likely be revised slightly upwards in light of the new data - the baseline scenario assumes a slight growth on average for the year 2023; only in a stressed scenario (with a total freeze on Russian gas …
According to the September wave of Consensus economics, inflation projections for Italy in 2023 stood on average at around 4.3 per cent, more than one point higher than the in previous month's estimates.
Still, in our baseline projection, the change in GDP is expected to remain positive in the average of 2023, as the economy is seen to be returning to growth in the second half of the year.
With respect to our July Economic Bulletin, growth forecasts are not expected to change much for this year, while they will be significantly reduced for the next.
A legislative proposal may be submitted by the Commission to the European Parliament and to the Council in the first half of 2023.
Firms are experiencing increasing turnover and hiring difficulties and, as we shall learn from one of the papers that will be presented in this conference, this can have a significant impact on investment decisions, employment growth and profits. 2
These prices have also been rising recently, exerting pressure on the costs of generating electricity from coal and gas: in May, emission allowance prices increased by 60 per cent over the previous year, exceeding €85/tonne.
Inflation, measured according to the EU's harmonized definition, exceeded 8 per cent in the euro area and 7 per cent in Italy in May.
The central scenario formulated at the time and its successive refinements continue to project positive growth in both 2022 and 2023.
While fossil fuel prices have risen everywhere, the rise in gas prices was less pronounced in the United States, though it has been accelerating in the last few months (with year-on-year increases of 53 per cent in February and 175 per cent in May).
All the more reason, bearing in mind that the same optimal price, that which correctly incorporates the externalities associated with emissions is subject to uncertainty in its calculation, while the technical instruments to achieve it give rise to differences of opinion, and it is therefore inevitable that we will have to move forward, at least in part, by trial and …
In May of this year, oil prices in the world markets rose by 65 per cent year-onyear.
In May, euro-area consumer price inflation reached 8.1 per cent on a 12-month basis, the highest value recorded since the Economic and Monetary Union was launched.
Global reviews will be conducted jointly by the FSB and IOSCO by end-2026, with the aim of assessing the appropriateness of the measures adopted by all jurisdictions and evaluating the need for further action at the global level.
The ROE expected by financial analysts for the main Italian banks stands at around 6 per cent, a similar level to that recorded in 2019.
For these countries, the IMF's 2021 growth projections stand at just 3.0 per cent, compared with prepandemic rates of around 5.0 per cent.
Starting in 2022, these surveys will be conducted on an annual basis.
It will be incumbent on future G20 presidencies to carry on the work that has been started this year.
In Italy, we expect this to happen in the first half of 2022.
For Italy, the IMF's projection for growth this year has improved from 4.9 to 5.8 per cent, while for 2022 it has been confirmed at 4.2 per cent.
They now expect an expansion of 5.9 per cent this year and 4.9 per cent in 2022.
Ms Wörsdörfer will present the main results of the IEA 's new flagship publication, 'Net Zero in 2050: A roadmap for the global energy sector', which will be out tomorrow.
According to Commission estimates, the European plan to become carbon-neutral by 2050 requires €350 billion of additional investments in 2021-2030. 8 In contrast, the whole EU budget expenditure for 2020 amounts to €155 billion. 9 While national governments spend much more, achieving the global climate targets must realistically assume that private finance will play a central role.
The increase is bound to continue: by 2020, an estimated 1.7 MB of data will be created every second for every person on earth.
The Government's budgetary provisions increase net borrowing, with respect to the current-legislation projections, by an average of 1.3 percentage points of GDP per annum in the three years 2019-2021, de-activating the safeguard clauses for next year and reducing, though only slightly, the amount for the following two years.
The tax on unincorporated business income was expected to reduce taxation by nearly €2 billion in the first year and about €1.3 billion from 2020.
On average, over the next three years, the budgetary provisions would generate resources of around €11 billion per year, enough to cover just under a third of the expansionary measures; the remainder will increase the deficit to the extent I have already mentioned.
For those who will benefit from the substitute tax regime from 2020, the 20 per cent preferential tax rate will reduce the average rate by about 7 points.
The 2019 deficit will come to 2.4 per cent of GDP , which is 1.2 percentage points higher than the current-legislation projection and more than half a percentage point above the Government's estimate for 2018.
It is important to underline that for the macroeconomic effects expected in 2019 to be fully deployed the measures need to be implemented from the beginning of the year.
Interest payments are expected to grow steadily, reaching 3.8 per cent of GDP in 2021.
Notwithstanding this revision, current legislation net borrowing is expected to continue to decrease, also thanks to the safeguard clauses (whose effect is equal to 0.7 per cent of GDP in 2019 and to 1.0 per cent from 2020 onwards): as a percentage of GDP, net borrowing is estimated to fall to 1.2 per cent in 2019, 0.7 per cent in …
The tax burden will decline from 42.2 per cent in 2017 to 41.9 per cent this year, mainly due to developments in direct taxes.
In the two years 2020-21 GDP is expected to expand by 1.1 per cent.
In July's Economic Bulletin we had forecast an increase in GDP of 1.3 per cent this year and of 1 per cent in 2019, assuming the full deactivation of the safeguard clauses on indirect taxation.
In the Government's programmes, the debt-to-GDP ratio, which is expected to reach 130.9 per cent at the end of this year, should decrease on average by
Just the revised GDP estimates for the last quarter of 2016 and the first quarter of 2017, released by Istat after the closure of our projections exercise, raises the outlook for the growth achieved so far in the current year by about 0.3 percentage points.
Growth in global demand is expected to continue and leading international forecasters are actually predicting that it will strengthen this year and the next.
In the first three months of this year Italy's GDP grew by 0.4 per cent, exceeding the expectations of the leading forecasters.
On 9 June we published the Bank of Italy's macroeconomic projections prepared as part of the Eurosystem staff macroeconomic projections: these suggest that GDP will rise by 1.0 per cent this year, before accelerating to 1.2 per cent in the subsequent two years.
Openness to trade, immigration, and foreign investment generally promote growth, while a decrease in these factors, especially if it occurs in a climate of increasing protectionism at global level, could create significant costs for the UK economy in terms of innovative capacity, competitiveness, and productivity growth.
Showing the newest 50 - the ledger has all 60.
Also said - not checkable as stated (12 newest)
Remarks about the future with no date, figure or likelihood that could be checked. They are kept on the record and shown here, but not scored.
Less obviously, but no less importantly, it can mitigate the uncertainties and information asymmetries that often affect private investment in developing economies, making it scarcer, more costly and more volatile than it could otherwise be.
Whatever the reason, where debt is unsustainable, it must be restructured; as a market-economy principle, this is true of
Today we shall also have the pleasure of hearing Professor Michael Weber's keynote speech and Philip Lane delivering the Marjoline Lecture whereas, tomorrow, Professor Pierpaolo Benigno will be giving a speech on the non-linearity of the Phillips curve - that elusive, mutable, but ultimately ever-resurgent 66-year old concept.
Spikes in global energy and commodity prices could not be neutralised by monetary policy, of course.
I am sure this conference will discuss the relative importance of several such propagation channels.
Anticipating rising general inflation, workers may pre-emptively demand higher wage increases and firms set higher prices.
To the extent that an increase in expected inflation is not immediately reflected in a change in nominal rates, agents will perceive a temporary decrease of the real rate, which may affect their decisions on the inter-temporal allocation of consumption and investment.
In the short term, this may in turn push aggregate demand and inflation in the same direction in which expectations initially moved. 2
The shift to digital channels will continue; appropriate actions need to be put into place to ensure that everybody can reap its benefits.
It has received a lot of attention over the years as an instrument to foster growth, reduce inequalities, increase employment, and alleviate poverty. 1 Financial inclusion may help people cope with macroeconomic and idiosyncratic shocks, as it facilitates financial planning and the intertemporal shift of financial resources.
Our seminar will be an opportunity to go beyond generalities and explore the most likely concrete challenges and trade-offs we need to face in the quantum era.
Experts agree that we are on the eve of a very significant technological change: one that will redefine our approach to data and to the tools we use to process them, and may well revolutionise important, even critical, aspects of the way financial institutions operate.