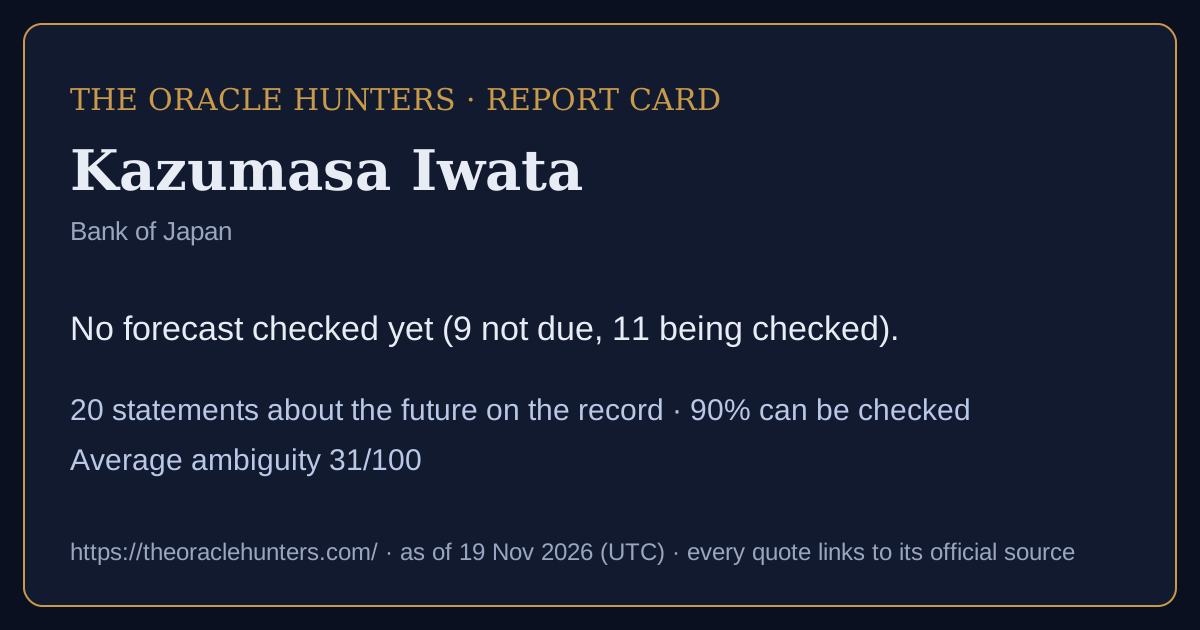
Kazumasa Iwata
Bank of Japan
Track record: No forecast checked yet (9 not due, 11 being checked).
20forecasts & commitments on the record
90%can be checked as stated
31average ambiguity (0-100)
0goalpost moves recorded
0confirmed U-turns
Timeline
came true partly did not not due / being checked / too vague
Calibration score: shown after 10 checked forecasts with a stated likelihood (now 0).
How they speak about the future: based on data 18, educated guess 2.
Kinds of claim: forecast 17, scenario (if… then) 3. · Download this report card as a picture
In the nine words
How to read this
Each box is one sentence a public figure or institution said about the future, word for word, with a link to the official text. Can be checked means it names what will happen, by when, and how likely - so it can be compared with official figures later. Too vague to check means it does not. Ambiguity (0-100) is how many different ways the sentence can be read. When the date passes, the forecast is compared with official data and marked came true, partly or did not come true. Labels judge the sentence, never the person. Full guide and glossary.On the record (20)
Given the low term- and risk premia across various financial markets, the low real long-term rate implies that any country which has higher expected growth rate, significantly above 2%, is liable to register the acceleration of asset prices. 9
If this wealth were not transferred to oil-producing countries but instead spent in Japanese markets, it could be expected to deliver a positive fillip to the growth of domestic demand.
At the same time, the basic loan rate applicable under the complementary lending facility (the standby lending facility through which the Bank will extend a loan at the request of a counterparty up to an amount not exceeding the value of that counterparty's collateral) was set at 0.75 percent.
From a longer-term perspective, however, consumer prices are expected, over time, to display trend increases given that the economy has expanded at an annual rate of around 2 percent over the last four years and that the expansion is expected to be long-lasting.
Production exhibited high quarter-on-quarter growth of 2.6 percent in the October-December quarter of 2006, but a downward reaction to this high growth coupled with adjustments in the IT-related sector will likely suppress growth in the January-March quarter of 2007.
The economy maintained a rate of growth of about 2 percent from fiscal 2003 to fiscal 2006, a pace which it seems likely to sustain during fiscal 2007.
Nevertheless, given the robustness and the flexibility of the economy it is likely to avoid a significant slowdown in the growth rate and to realize a soft landing, returning to its potential growth path from the current 2.0-2.5 percent by late 2007, with a gradual decline in the rate of inflation.
It may be noted that the additional flotation of government bonds to frontload the rollover of existing government bonds concentrated in fiscal 2008 has made it more difficult to maintain the reserve target. 4
Market participants, who once appeared to be skeptical of our scenario of registering a 0.3 percent rise in the core CPI in fiscal 2006, now seem to anticipate the likely end of the current policy regime within one year, as observed in euroyen futures market interest rates.
If it exceeds the real long-term market interest rate, then deflation will cease to exist.
Furthermore, if in the future the fertility rate remains at the current level (which is 1.29), then 'the last baby will be born in about eight hundred years'. 1 South Korea, Taiwan, China and Australia will follow a similar process in the absence of immigration, although the speed of their ageing process is divergent (Figure 1).
Nevertheless, the actual average economic growth rate since the bursting of the bubble economy has not been negative, and the expected growth rate cited by corporate managers has returned to slightly above 1 percent.
In China, the working-age population ratio increased from 55 percent in 1975 to 60 percent in the early 2000s, and is expected to surpass 70 percent by 2010.
The total population is forecast to peak at 128 million in 2006 and decline to 100 million in 2050.
Thus, the U.S. economy is highly likely to continue growing at around 4 percent from the fourth quarter of this year through the end of next year.
Another reason for pessimistic private forecasts is that the U.S. economy may rapidly slow down in mid-2004 after the effects of recent tax cuts have run their course.
One of the reasons why private forecasts for fiscal 2004 are more pessimistic than the Bank's forecast is that they anticipate inventory adjustment or a slowdown in business fixed investment.
In the United States, inventory is also at a low level, and inventory investment is expected to increase, thus offsetting the slowdown in the growth of final demand until mid-2004.
The euro area has hit bottom and is expected to be on a growth track of around 1.5 percent in 2004 as business sentiment improves.
Private forecasts of real GDP growth for fiscal 2003 and 2004 are generally lower than the Bank's forecast in the mid-2 percent range for both years as presented in Outlook and Risk Assessment of the Economy and Prices (hereafter the Outlook Report) in October 2003.
Also said - not checkable as stated (12 newest)
Remarks about the future with no date, figure or likelihood that could be checked. They are kept on the record and shown here, but not scored.
Second, we should put emphasis on the need to deal with the euphoria brought about by higher expected growth and the sharp drop in "finance premium" during the bubble period.
On the other hand, if we want "household monetary expenditure" to be reflected in the CPI, then the net acquisition method (in the sense of excluding the transaction of existing dwellings) may be preferred, since this treats the purchase of housing the same as for durable consumer goods.
This method also may involve including the asset component in the CPI, of particular relevance if the land is included (Eiglsperger (2006)).
This may reflect a stable share of shelter costs in the household budget.
After constructing the wealth price index as the weighted geometric mean of current product price inflation (GDP deflator) and future price changes represented by aggregate asset price of the national wealth in the national accounts, he argued that the BOJ could have envisaged future inflation if the wealth price index had been employed in the mid-1980s, in addition to the …
Black argued that the long-term interest rate will remain positive under the 'liquidity trap' in the presence of a zero bound on nominal short rates, because of the more-than-usual term premiums and the expectation of future development of the short-term interest rate at zero embedded in the longterm interest rate.
The commitment on the duration of the zero interest rate policy suggests that the shadow interest rate will be negative, as long as deflation is expected to persist into the future; the longer the duration of the zero nominal interest rate, the larger the size of negative interest rate. 10
As long as the marginal utility of money remains positive, the 'satiation of money holdings' will not emerge even though the zero bound on short-term interest rates appears in the economy.
Yet it may be noted that the effect on the risk premium or the credit spread through ortfolio rebalancing under the zero short-term interest rate is not excluded, though the effect seems to be small (Kimura and Small (2006)).
Further, the new framework introduced two perspectives on examining economic activity and prices; the first perspective is examining, as regards economic activity and prices one to two years in the future, whether the outlook deemed most likely by the Bank follows a path of sustainable growth under price stability.
For instance, excessive investment induced by sustained expansionary monetary policy may give rise to undesirable wide fluctuations of economic activity.
The conduct of monetary policy is now based on the new framework announced in March this year and on the findings from examining the risks affecting the economic outlook that are described in the Outlook for Economic Activity and Prices (hereafter the Outlook Report).